A disputed payment needs more than a reply
A chargeback dispute starts when a cardholder challenges a payment through their card issuer. For the merchant, that creates a financial case with a response deadline, evidence requirements and an outcome decided through the payment dispute process.
The work can reach far beyond finance. Customer service may hold the conversation, the warehouse may have inspection photos, and the payment provider may show a refund that hasn't appeared in the support ticket.
A useful dispute management system connects those records to the right action. Choosing one starts with distinguishing card chargebacks from the invoice disputes and deductions handled by B2B accounts receivable teams.
- A chargeback dispute requires a timely decision to accept the claim or challenge it with relevant evidence.
- Stripe and Adyen combine payment operations with dispute tools; Chargeflow and Justt offer dedicated chargeback handling.
- HighRadius and FIS GETPAID address B2B deductions and receivables disputes, which need different workflows from card chargebacks.
- Claimlane manages the returns and warranty cases that can provide context for a payment dispute, while bank responses remain with the payment or dispute platform.
Chargeback dispute, refund and invoice dispute explained
A refund is a payment returned by the merchant through its payment process. A card dispute begins with the cardholder and issuer, and can lead to a chargeback against the merchant.
A B2B invoice dispute concerns an amount a business customer contests, such as a price difference, shortage or disputed return credit. A deduction occurs when the customer pays less than the invoiced amount.
Those differences determine the workflow. A card dispute needs payment-provider evidence submission. An invoice discrepancy may need sales approval, delivery documentation and an accounting adjustment.
A business accepting both cards and payment on account may need both capabilities. The word dispute on a product page doesn't establish which process the software supports.
Why customers dispute card payments
A dispute can concern an unauthorised transaction, an unreceived product, a product that wasn't as described or another payment issue. The reason supplied with the case should guide the investigation.
The merchant shouldn't assume that every dispute is fraud. A customer may have a valid complaint, while another case may involve a misunderstanding or a claim contradicted by the records.
A practical review checks the payment and order alongside the customer's explanation. The team should establish what happened before choosing a response.
How does the chargeback dispute process work?
The payment provider notifies the merchant of a dispute and provides the relevant details. The merchant then determines whether to accept it or submit evidence challenging the claim.
Stripe's response guidance explains that its users should examine the complaint, assemble the relevant records and submit their response through the dispute process. The cardholder's bank reviews the response and decides the outcome.
The team should use the deadline attached to the actual case. A generic internal target doesn't replace the payment provider's submission requirements.
Operationally, the record needs an owner, a decision, confirmation of any submission and the final financial result. A response marked as prepared is different from a response successfully submitted.
Collect evidence that answers the complaint
Evidence should explain why the disputed payment is valid in relation to the stated complaint. A delivery record and a refund confirmation establish different facts.
Stripe recommends organising evidence clearly, keeping it relevant and explaining what the supporting records demonstrate. Sending an entire customer history can bury the important detail.
- Payment and order details that identify the transaction.
- Relevant delivery or service records.
- Customer messages concerning the disputed issue.
- Applicable cancellation or refund terms where relevant.
- Confirmed refunds, returns or other completed actions.
The internal case can hold the complete history, while the submitted response uses the relevant evidence in the provider's accepted format. Sensitive or unrelated material shouldn't be included simply because it's available.
What does automated dispute management handle?
Automated dispute management can cover receiving case data, gathering records, preparing evidence, assigning work and submitting responses. The exact scope depends on the product and its connections.
Stripe Smart Disputes, for example, automates evidence collection, compilation and submission for eligible card disputes. Its eligibility depends on factors including the dispute reason, payment method and available evidence.
Buyers should ask what happens outside the automatic path. Missing delivery information, conflicting refund records or an unsupported payment connection should lead to visible follow-up work.
The evaluation should also distinguish an automated recommendation from an executed action. A suggested response still creates manual work if someone must gather the documents and submit it separately.
What are the best dispute management platforms?
The most useful shortlist depends on the type of dispute. Stripe and Adyen are candidates for merchants seeking payment processing and dispute tools together. Chargeflow and Justt are candidates for dedicated chargeback operations, while HighRadius and FIS GETPAID address receivables disputes and deductions.
The following comparison is an editorial assessment of fit based on published capabilities. It isn't a ranking based on independently tested recovery results.
| Platform | Relevant work | Key evaluation question |
|---|---|---|
| Stripe | Payment refunds, card disputes and eligible automated responses | Which disputes qualify for automation in the merchant's account? |
| Adyen | Payments, refunds and dispute handling through its Customer Area or API | Which payment methods and dispute stages are supported? |
| Chargeflow | Dedicated chargeback automation, alerts and prevention | Which payment and evidence sources connect to the workflow? |
| Justt | Tailored dispute arguments and chargeback operations across payment providers | How are evidence gaps and merchant-specific exceptions handled? |
| HighRadius | Customer deduction research and supporting-document matching | Can the platform handle the business's deduction types and customer portals? |
| FIS GETPAID | AR deduction and dispute assignment, tracking and escalation | Can finance, sales and operations coordinate the required approvals? |
| Claimlane | Returns, warranty claims and related operational follow-up | Can the product issue and completed outcome stay connected to finance's case? |
Claimlane appears here because product claims can require financial follow-up. It doesn't replace a card dispute submission platform or a general AR ledger.
Best platforms for payment refunds, chargebacks and disputes
Stripe
Stripe is a practical starting point for a merchant already processing payments through it. Its documentation covers refunds, dispute responses and Smart Disputes for eligible automated evidence handling.
That fit should be assessed against the merchant's account, payment methods and required features. Existing payment processing doesn't establish that every dispute will qualify for automation.
Adyen
Adyen provides refund operations and dispute handling through its Customer Area and Disputes API. The API can retrieve case information, accept disputes, upload defence documents and submit a defence.
Adyen documents limitations, including that not all dispute types can be defended. Buyers should confirm the supported workflow for their payment methods before treating the API as a complete answer to every case.
Choosing an end-to-end payment platform for ecommerce
For ecommerce businesses seeking payment acceptance, refunds and dispute tools in the same payment setup, Stripe and Adyen belong on the shortlist. Selection should follow a demonstration of the merchant's actual transaction lifecycle.
A suggested demonstration starts with a payment, follows a partial refund and then introduces a dispute. The team should check whether the refund history remains visible, how evidence is attached and how the final outcome reaches reporting.
The comparison should also cover local payment methods, currencies, access controls and reconciliation needs. These are buying criteria to verify, rather than a claim that every feature is available under every agreement.
An end-to-end payment platform still needs accurate information from fulfilment and support. A payment record alone may not explain the condition of a returned product.
When a dedicated chargeback platform makes sense
A dedicated platform is worth considering when the payment provider's workflow leaves substantial evidence gathering or coordination with the merchant. Multiple payment providers can also create separate queues and reporting views.
Chargeflow publishes capabilities for chargeback automation, alerts and prevention. Justt describes tailored evidence and dispute arguments, with support for businesses operating across payment providers and markets.
A useful evaluation asks each vendor to identify the systems it can read from, the actions it submits and the exceptions the merchant still owns. The commercial agreement should explain fees and the scope of the service.
Published capabilities justify a shortlist. They don't prove that a provider will deliver the highest win rate for a particular merchant.
Best dispute management software for enterprise AR teams in 2026
For enterprise accounts receivable teams, HighRadius and FIS GETPAID are relevant candidates when the workload centres on deductions, contested invoices and cross-team follow-up.
HighRadius for deduction research
HighRadius publishes capabilities for capturing customer claims, linking supporting documents and comparing deductions with pricing or promotion records. That makes it a candidate when research across customer portals and documentation is a major part of the work.
FIS GETPAID for dispute coordination
FIS GETPAID includes deduction and dispute management with assignment, notifications, tracking and escalation. Its collaboration offering connects sales, customer service, operations and customers through a dispute network.
The buying team should test approval controls, account relationships and ERP updates against its own process. Enterprise suitability should be demonstrated through those requirements, rather than inferred from the size of the vendor.
Top dispute management platforms for B2B companies
The B2B shortlist should follow how customers pay and what they contest. A business selling on account needs different capabilities from one mainly handling card-funded orders.
HighRadius is worth evaluating for deduction validation and supporting-document research. FIS GETPAID is worth evaluating where dispute ownership and collaboration sit within a broader AR process.
For B2B card chargebacks, the relevant payment provider or a dedicated chargeback platform remains part of the process. An invoice dispute tool shouldn't be assumed to submit evidence to card issuers.
Where a retailer contests a delivery because products arrived damaged, the product claim and invoice dispute should remain linked. The teams need to agree what happened to the goods before recording the appropriate financial outcome.
What should a dispute management system record?
A useful system shows the contested amount, the reason, the evidence, the owner and the next action. The record should also identify the payment or invoice to which the dispute belongs.
For teams designing the workflow, useful fields include:
- Customer, account and transaction references.
- Disputed amount and currency.
- Reason and relevant product or invoice lines.
- Evidence location and completeness.
- Owner, deadline and approval status.
- Confirmed submission, settlement or accounting action.
Card disputes and AR cases can share some fields without sharing the same statuses. A bank response under review is different from a credit note waiting for internal approval.
Compare recovery results with consistent measures
A dispute win rate is difficult to interpret without its denominator. Wins among challenged cases answer a different question from wins among every dispute received.
A proposed vendor comparison should track the share of eligible cases challenged, final outcomes, recovered value after fees and manual handling time. Pending cases should remain separate from completed results.
For AR disputes, suitable measures might include disputed balance, case age, recovery of invalid deductions and the time needed to approve valid credits. These are proposed measures to collect, not industry benchmarks.
The comparison should group similar case types. A change in the mix of disputes can affect the headline result without showing that the software improved.
Keep refunds and chargebacks from creating duplicate work
Support may be preparing a refund while finance receives a dispute notification. Before either team acts, the current payment and dispute status should be checked.
Stripe documents duplicate-reimbursement risks when refund and dispute activity overlap. If a pending refund fails because the charge was disputed, its guidance is to accept or challenge the dispute instead of refunding. Teams using other providers should follow that provider's supported process.
The internal record should distinguish a promised refund from a submitted refund and a confirmed result. A support message isn't proof that the money has moved.
For B2B accounts, the same control principle applies to credits. An approved credit note should remain connected to the disputed invoice so another team doesn't independently approve the same adjustment.
Test the handoffs before expanding automation
A software demonstration should include situations that currently require staff to intervene. Straightforward cases alone won't show whether the new process can handle the actual workload.
Suggested scenarios include missing evidence, an existing partial refund, a customer disputing only part of an invoice and a rejected system update. The team should follow each case through ownership, decision and confirmed financial action.
For card disputes, confirm that each case has a designated submission route. For AR disputes, confirm which system owns the balance and posts the final adjustment.
Expansion should follow evidence that the workflow works for the selected cases. Automatic handling needs a clear route for the cases that fall outside it.
Where Claimlane fits in dispute management
Some payment disputes involve a product issue that already exists in a support conversation: damaged goods, an unresolved return or a warranty claim awaiting action. Claimlane manages that operational work.
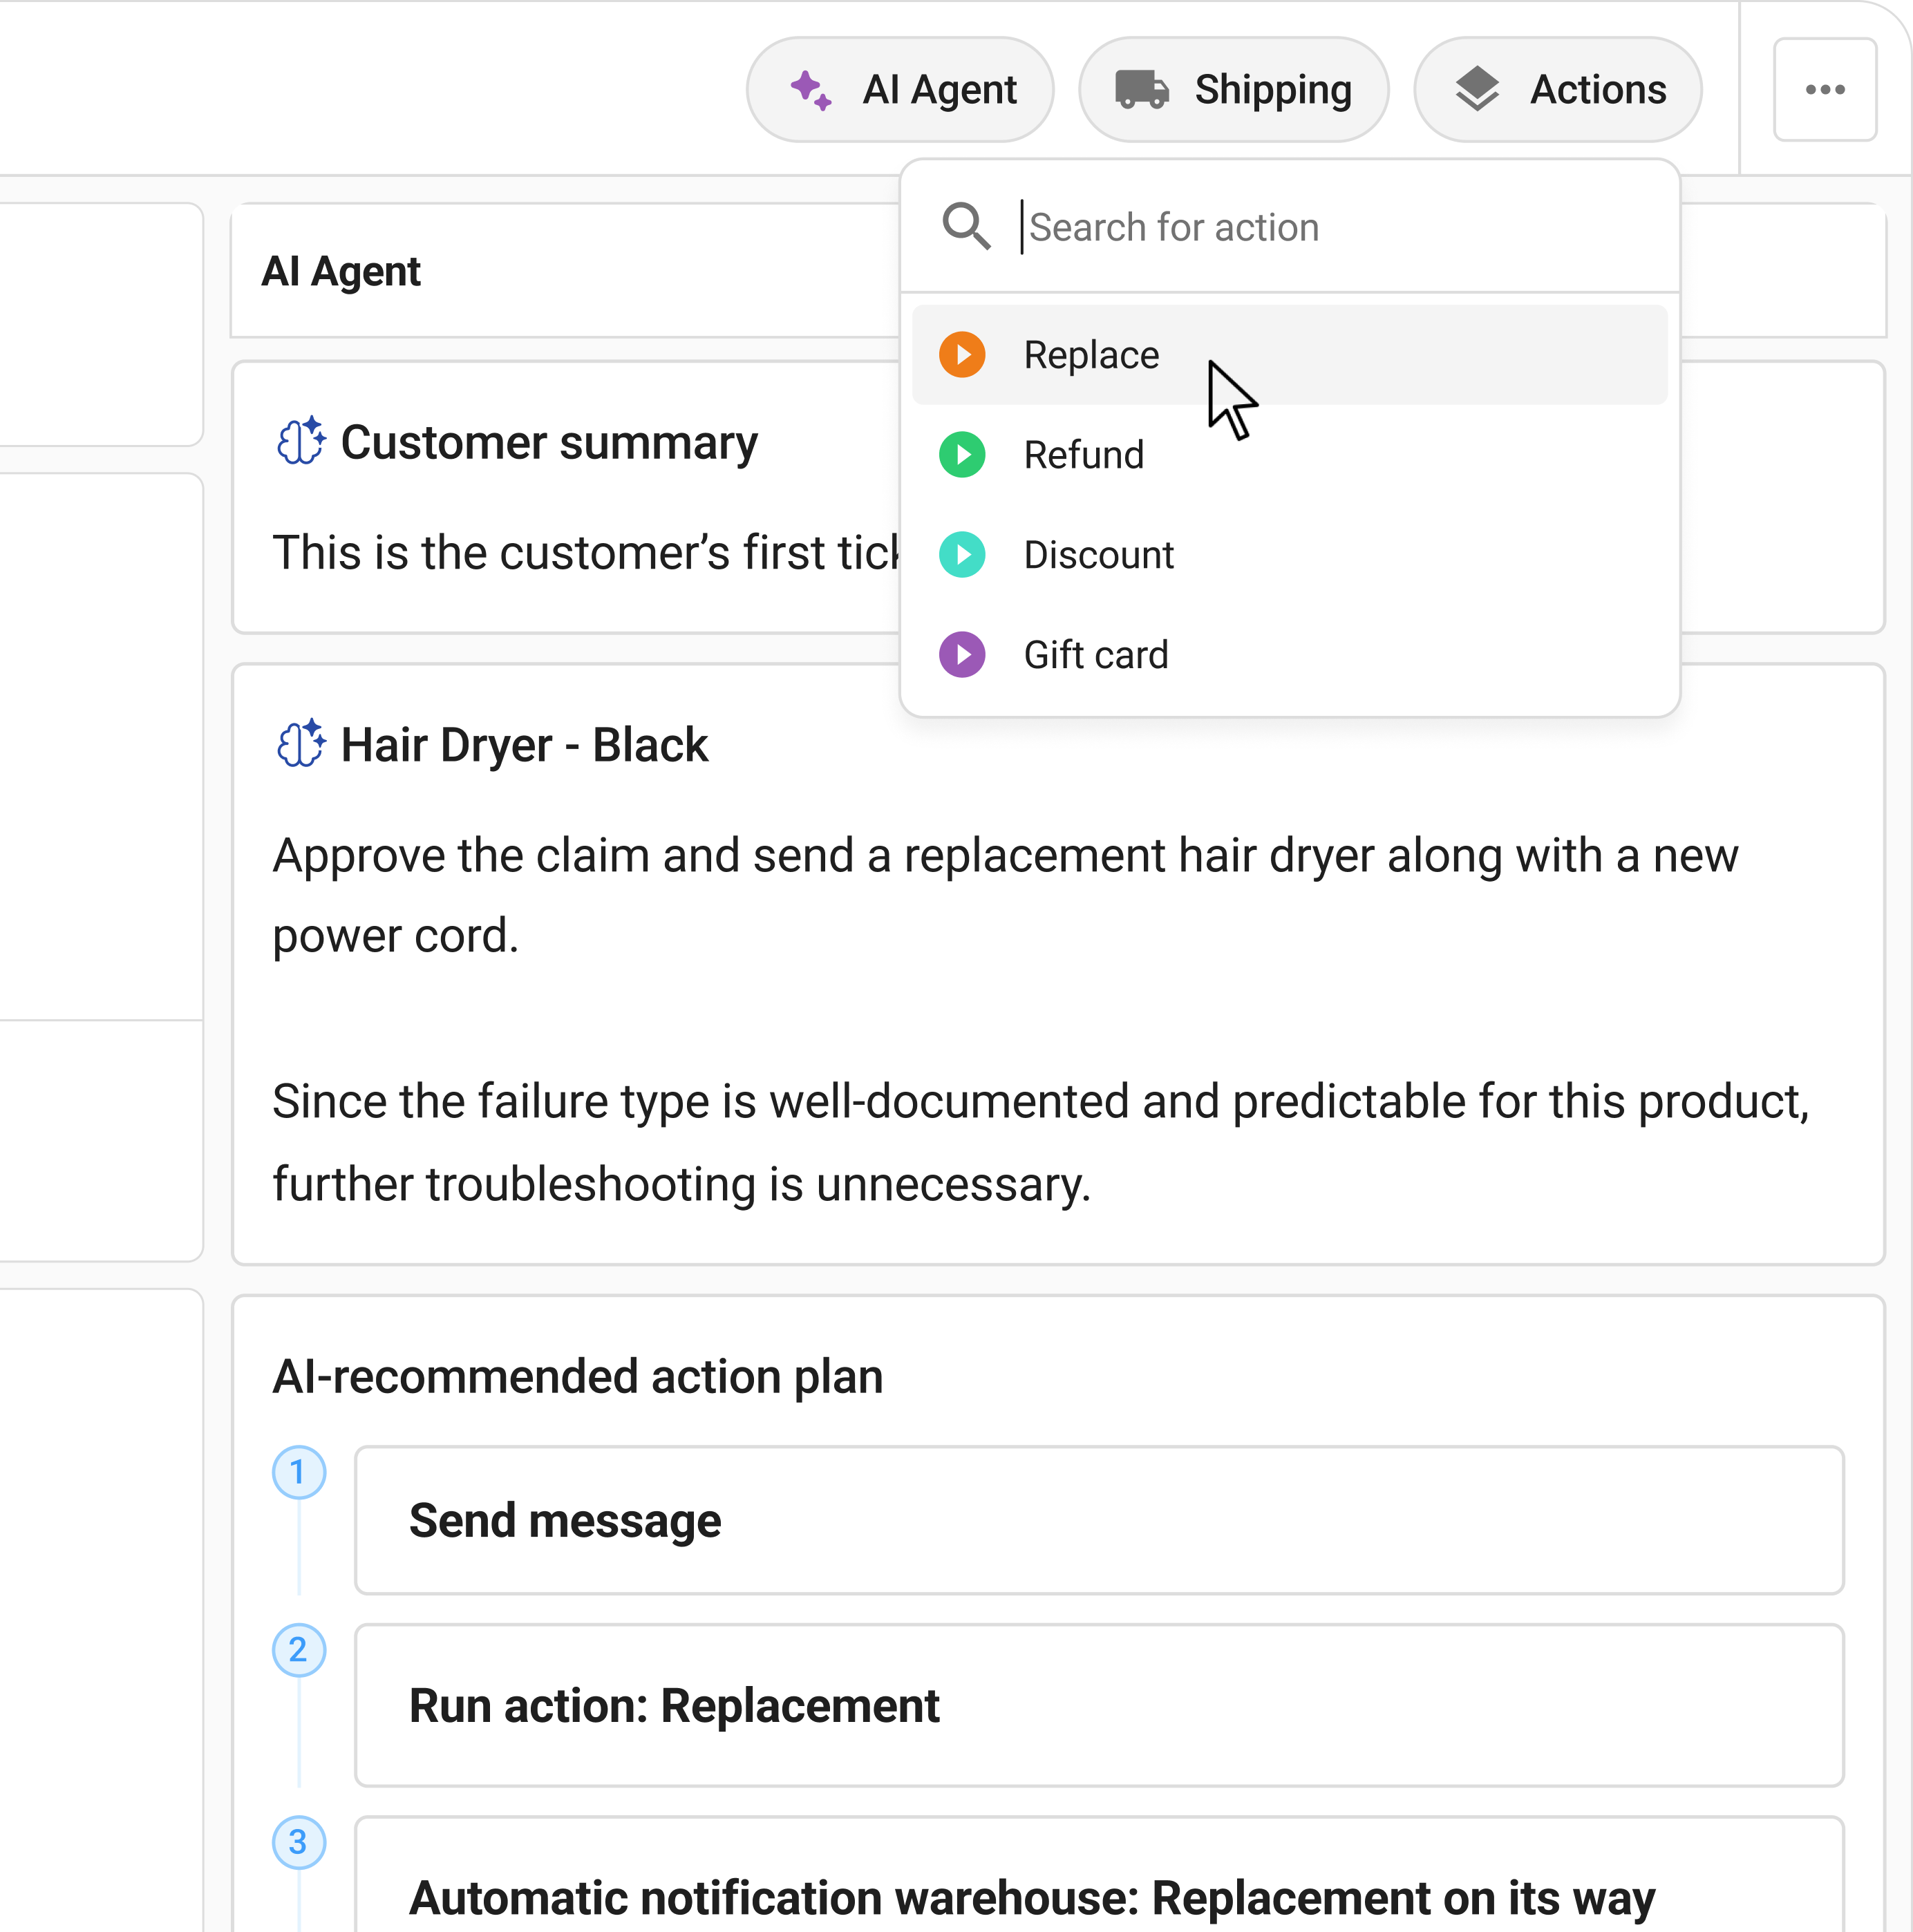
Claimlane's returns and warranty workflows support case routing and actions such as replacements, refunds and ERP updates through connected systems. These capabilities help teams keep the approved outcome and follow-up work together.
Samira Nobakhti-Afshar describes the importance of handling product issues for retail partners:
The customer's issue gets solved much faster, and that is absolutely key. We want a good and effective partnership with our retailers.
Samira Nobakhti-Afshar, Sales Support Specialist, Konges SløjdThe payment or AR team can use the relevant case history when reviewing a disputed amount. Any automatic transfer of evidence needs to be confirmed for the selected setup; it shouldn't be assumed from the presence of an integration.
Claimlane's role here is product claims handling. The customer quote describes that experience, rather than measured chargeback prevention or bank dispute win rates.
Claimlane has a 4.8/5 rating on G2.
Frequently asked questions about chargeback disputes
Connect the disputed payment to what actually happened
Good chargeback dispute management starts with a clear record and an appropriate response. The right platform depends on whether the team is defending a card payment, investigating a deduction or resolving the underlying product issue.
Payment providers, dedicated dispute tools and AR software each address different parts of that work. Clear ownership keeps the customer record, financial decision and final action connected.
Brands and retailers can book a Claimlane demo to review how returns, warranty claims and retailer cases can support a more organised post-purchase process.